In 2024, the IRS reported that roughly 90% of all individual filers claimed the standard deduction, leaving only about one in ten taxpayers to itemize (IRS, 2024). That gap means most people never explore whether listing mortgage interest, state taxes, or charitable gifts could lower their bill. This guide walks you through the mechanics of each approach, shows how to run a quick side‑by‑side comparison, and highlights the life events that often tip the scales. You’ll also learn why the decision isn’t set in stone and how a few minutes with last year’s return can reveal hundreds of dollars in missed savings.
Key Takeaways
– About 90% of filers take the standard deduction, per IRS filing statistics for 2024 (IRS, 2024).
– The standard deduction for single filers rose to $15,000 in 2025, while married couples filing jointly see $30,000 (IRS, 2025).
– Itemized deductions are dominated by state and local taxes, mortgage interest, and charitable giving, which together account for roughly 90% of all itemized claims (Tax Foundation, 2023).
– If your eligible expenses exceed the standard deduction by even $1, itemizing saves you money (IRS, 2024).
What Is the Standard Deduction?
The standard deduction is a flat amount the IRS lets you subtract from adjusted gross income without any paperwork, and it varies by filing status. In 2025, single filers can deduct $15,000 and married couples filing jointly can deduct $30,000 (IRS, 2025).
Because it requires no receipts or schedules, the standard deduction is the default choice for most taxpayers. You simply enter the amount on Form 1040 and move on. But the simplicity comes with a trade‑off: you cannot also claim individual expenses like mortgage interest or large medical bills.
If your financial life is straightforward—renting, no major medical costs, modest charitable giving—the standard deduction usually wins. Have you ever wondered whether a few extra receipts could change the outcome?
How Do Itemized Deductions Work?
Itemizing means listing each qualifying expense on Schedule A and adding them up to replace the standard deduction. You can deduct state and local taxes up to $10,000, mortgage interest on up to $750,000 of debt, charitable gifts, and medical costs that exceed 7.5% of your AGI (IRS, 2024).
The process demands more record‑keeping, but it can pay off when your total eligible expenses surpass the standard deduction. Many people discover they qualify after a year with high medical bills or a new home purchase. Do you keep a folder for tax‑related receipts throughout the year?
Software or a tax professional can automate the comparison, yet understanding the categories helps you plan ahead. For example, bunching charitable donations into a single year can push you over the threshold.
When Does Itemizing Beat the Standard Deduction?
Itemizing makes sense only when your allowable expenses exceed the standard deduction for your filing status. In 2024, the standard deduction for a single filer was $14,600, so any itemized total above that amount reduces your taxable income further (IRS, 2024).
For instance, if you paid $8,000 in mortgage interest, $5,000 in property taxes (capped at $10,000 SALT), and $3,000 in charitable gifts, your itemized total would be $16,000—$1,400 more than the standard deduction. That extra $1,400 at a 22% marginal rate saves about $308 in federal tax.
Life events like buying a home, having a baby, or facing large medical bills often create a temporary window where itemizing wins. Ask yourself whether this year’s expenses are unusually high compared with a typical year.
Common Itemized Deduction Categories
The biggest itemized deductions for most households are state and local taxes, mortgage interest, and charitable contributions. Together they represented roughly 90% of all itemized claims in 2023 (Tax Foundation, 2023).
Medical expenses can be deducted only to the extent they exceed 7.5% of AGI, which makes them less common but valuable in high‑cost years. Miscellaneous deductions like unreimbursed employee expenses were eliminated for 2018 through 2025, so they no longer apply.
Knowing which categories exist helps you gather the right documents early. Have you collected your property tax bills and mortgage interest statements for the year?
How the SALT Cap Affects Your Decision
The Tax Cuts and Jobs Act capped the state and local tax deduction at $10,000, which dramatically reduced the benefit of itemizing for residents of high‑tax states. In 2023, the average SALT deduction claimed by itemizers fell to just under $9,500 (Tax Foundation, 2023).
If you live in a state with high income or property taxes, you may hit the cap quickly. For example, a homeowner paying $12,000 in property taxes and $5,000 in state income tax can only deduct $10,000 total, losing $7,000 of potential deductions. That shortfall often makes the standard deduction the better choice.
Consider whether accelerating property tax payments or timing charitable gifts could help you maximize the limited SALT space. For more on timing strategies, see our guide on tax‑loss harvesting.
Standard Deduction Amounts Over Time
The standard deduction is indexed for inflation and has risen steadily. In 2020 it was $12,400 for singles, climbing to $15,000 by 2025 (IRS, 2025). Married couples saw a similar jump from $24,800 to $30,000 over the same period.
These increases mean that a taxpayer who itemized in 2020 might find the standard deduction more attractive today without any change in expenses. Checking the current year’s numbers each January takes only a minute.
Why does the IRS adjust the deduction annually? It prevents “bracket creep” where inflation pushes people into higher tax brackets without real income growth.
Should You Reevaluate Each Year?
Yes, because both your expenses and the standard deduction change annually. In 2025, the standard deduction for singles rises to $15,000, while the SALT cap remains $10,000 (IRS, 2025). A year with high medical costs or a new mortgage can flip the calculus.
Run a quick comparison using last year’s return: add up your actual itemized expenses, then compare the total to the current year’s standard deduction. If the difference is less than $500, the standard deduction’s simplicity may outweigh the small savings. For investors, understanding how capital gains interact with your deduction choice matters; see how capital gains taxes work.
Tax software often runs this comparison automatically, but knowing the mechanics lets you spot errors. Could a one‑time windfall like an inheritance make itemizing worthwhile this year?
Practical Steps to Decide This Tax Season
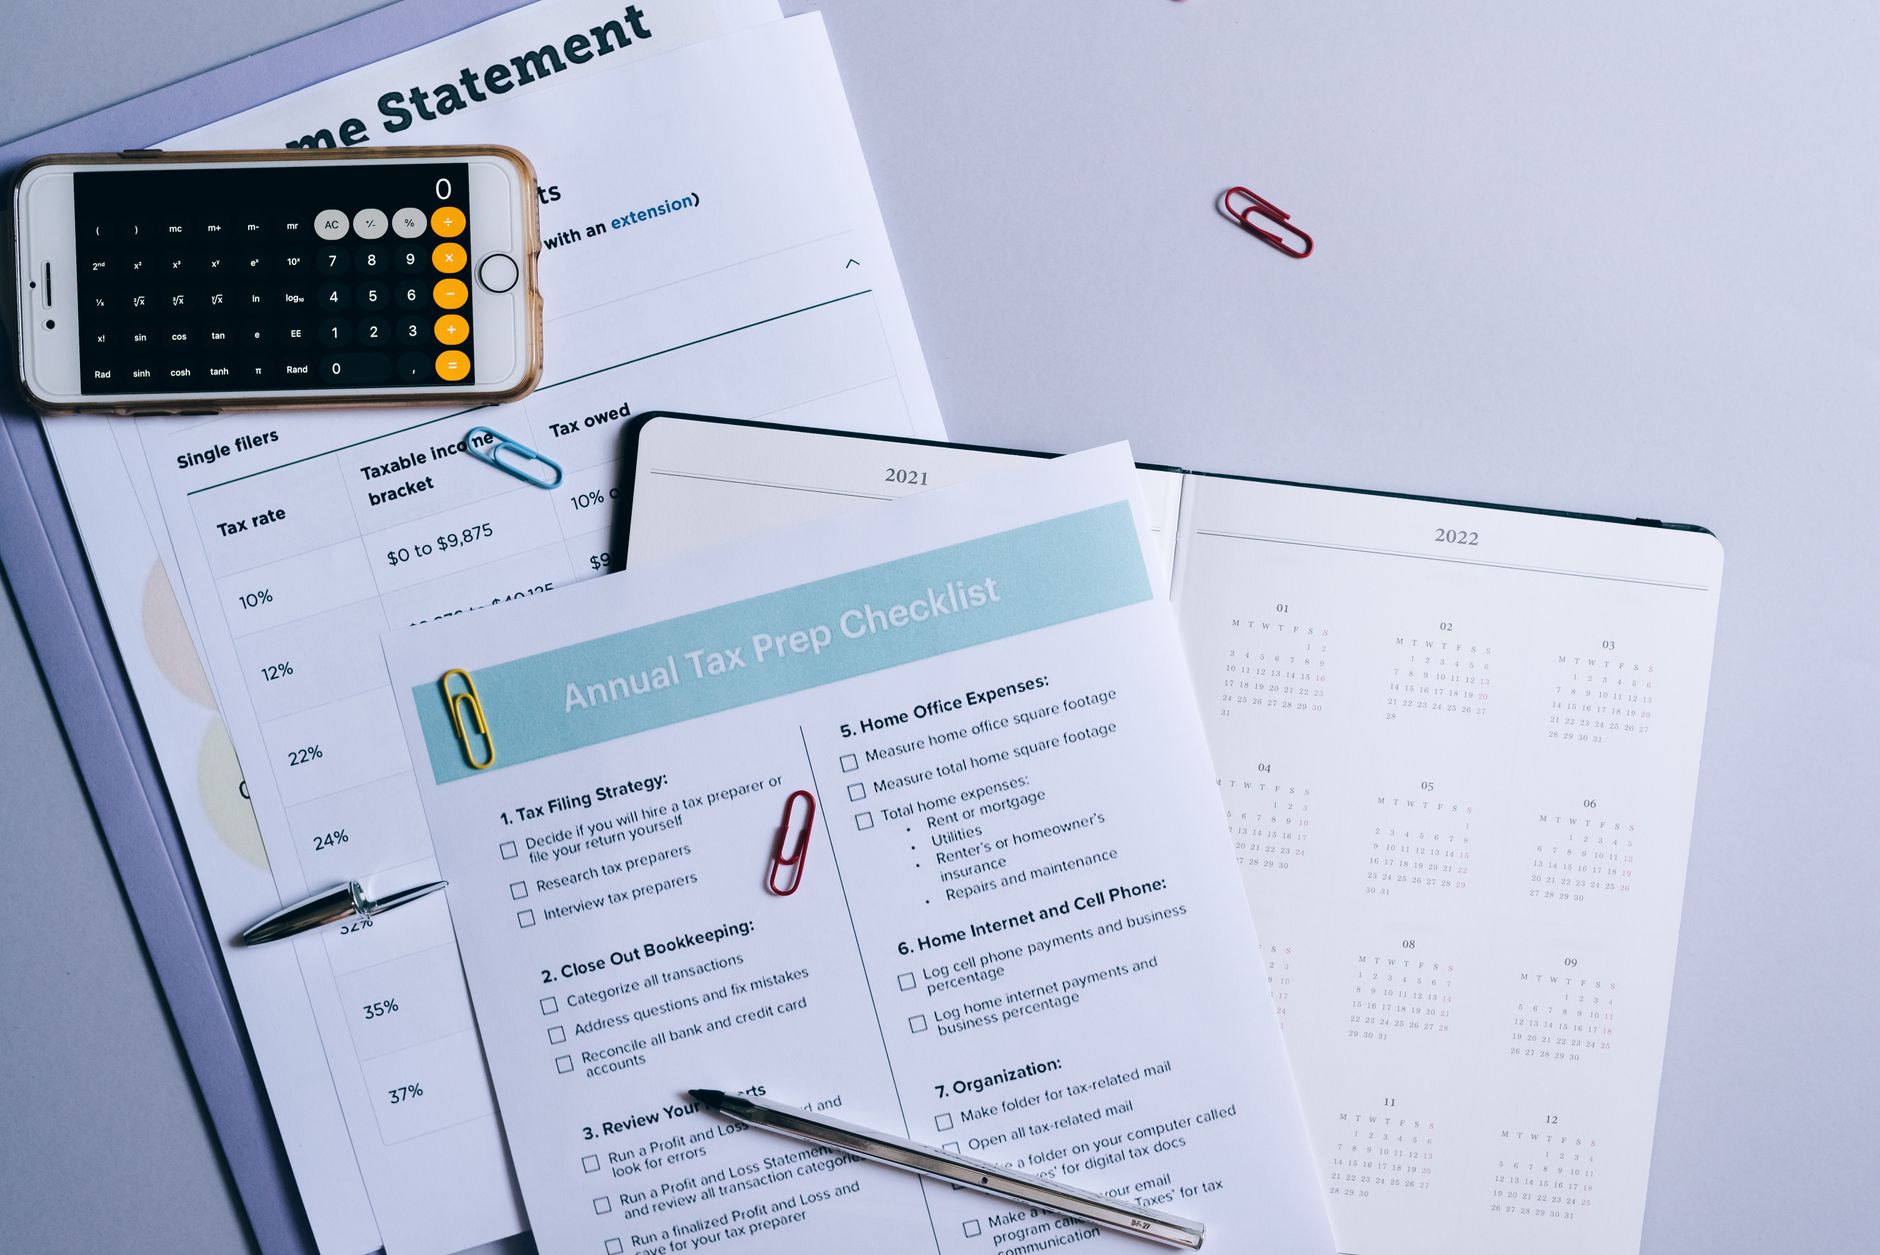
Start by collecting all potential itemized receipts: mortgage interest statements, property tax bills, charitable donation records, and medical invoices. Next, use your tax software’s “compare” feature or manually total the categories on Schedule A. Do this before you file to avoid last‑minute scrambling.
If the itemized total exceeds the standard deduction, file Schedule A; otherwise, take the standard deduction and save the paperwork. Remember that you can switch methods each year—there’s no lock‑in.
Finally, keep a copy of your workpapers for at least three years in case the IRS requests documentation. A little organization now can prevent a headache later.
Frequently Asked Questions
Can I switch between standard and itemized deductions each year?
Yes, you choose the method that gives you the lower tax liability each filing season; there is no requirement to stick with one.
What if my itemized deductions equal the standard deduction?
If they’re equal, the standard deduction is simpler and avoids Schedule A, so most taxpayers take it.
Does the SALT cap apply to both single and joint filers?
The $10,000 cap applies per return, so married couples filing jointly share the same limit.
Are there any deductions I can claim without itemizing?
Above‑the‑line deductions like IRA contributions, student loan interest, and HSA contributions are available regardless of which deduction method you choose.
How do I know if my medical expenses are deductible?
Only the portion exceeding 7.5% of your adjusted gross income counts; for example, with a $50,000 AGI, expenses above $3,750 are deductible.
Conclusion
- The standard deduction covers about 90% of filers and requires no extra paperwork.
- Itemizing pays off when your eligible expenses—especially mortgage interest, SALT, and charity—exceed the standard amount.
- Reevaluate annually because inflation adjustments and life changes can shift the advantage.
Sources
- Internal Revenue Service, “Standard Deduction Amounts for 2025”, retrieved 2026-09-28, https://www.irs.gov/newsroom
- Internal Revenue Service, “Filing Statistics 2024”, retrieved 2026-09-28, https://www.irs.gov/newsroom
- Tax Foundation, “Itemized Deduction Breakdown 2023”, retrieved 2026-09-28, https://taxfoundation.org/
This article is for educational purposes only and does not constitute financial advice. Investing involves risk, including loss of principal.
Pingback: Tax Deductions vs Credits: Differences and How to Claim Both - WealthForge